What is the market overview and industry significance of User Acquisition For Games Market?
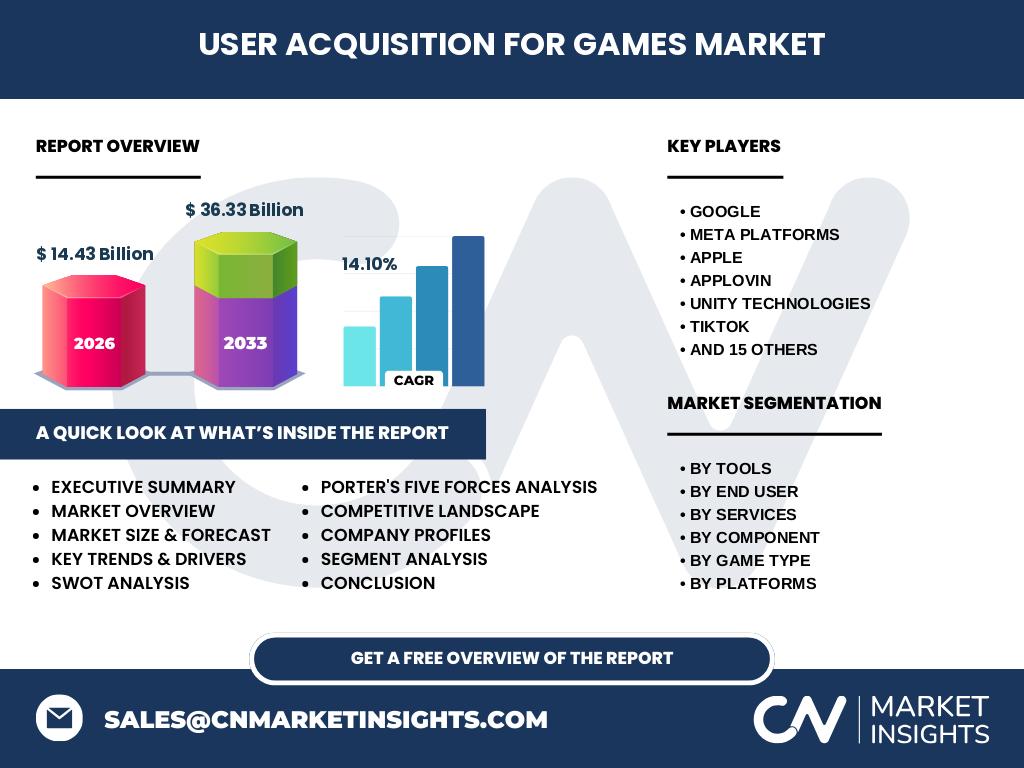
The User Acquisition For Games Market is valued at 14.43 Billion in 2026, serving as the critical growth engine for modern game publishers and developers. Our analysis indicates that navigating privacy regulations from bodies like the European Data Protection Board requires sophisticated analytics and attribution tools to sustain player acquisition velocity across mobile, PC, and console ecosystems.
Structural Growth Drivers and Restraints
Market expansion is heavily propelled by programmatic advertising platforms and advanced identity resolution solutions, driving a projected CAGR of 14.10%. However, growth faces severe restraints from tightening iOS and Android tracking policies, forcing developers to pivot toward contextual targeting, first-party data strategies, and sophisticated fraud prevention solutions to protect marketing budgets.
Emerging Trends and Growth Patterns in User Acquisition For Games Market
The shift toward automated, AI-driven creative optimization tools and cloud-based solutions is redefining campaign execution. Performance marketing services are increasingly integrating with influencer and affiliate marketing channels, allowing market participants like AppLovin and Unity Technologies to automate personalized player acquisition journeys across global social media platforms.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic lockdowns triggered an unprecedented surge in gaming engagement, inflating user acquisition demand across mobile and online game segments. As macroeconomic pressures normalized post-pandemic, the User Acquisition For Games Market shifted away from speculative spending toward disciplined, ROAS-focused monetization and retention optimization tools managed by specialized agencies.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of tech giants like Google, Meta Platforms, and Apple alongside specialized AdTech innovators such as AppsFlyer, Singular, and Adjust. Industry consolidation is accelerating as demand side platforms acquire cross-promotion networks to build closed-loop attribution ecosystems that withstand stringent privacy frameworks.
Executive Summary of User Acquisition For Games Market
Our comprehensive research values the User Acquisition For Games Market at 14.43 Billion in 2026, expanding rapidly to 36.33 Billion by 2033 at a CAGR of 14.10%. Success in this expanding sector demands heavy investment in cross-promotion platforms, managed services, and advanced data management solutions to navigate privacy headwinds.
Market Forecast and Trajectory Through 2033
Propelled by surging demand across console, PC, and mobile game types, the User Acquisition For Games Market is projected to scale from 14.43 Billion in 2026 to 36.33 Billion by 2033. This robust growth represents a steady CAGR of 14.10%, underpinned by rising investments in influencer marketing and programmatic media buying.
Segmentation Analysis of the Industry
Segmentation spans components, tools, services, game types, platforms, and acquisition channels. Tools such as fraud detection and attribution solutions form the technical backbone, while game publishers, developers, and advertising agencies utilize managed and consulting services to execute paid, organic, and social media acquisition campaigns effectively.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America and Asia-Pacific leading due to high smartphone penetration and mature gaming studios. Regulatory constraints in the EU under GDPR heavily influence regional tooling adoption, favoring privacy-compliant customer data platforms and measurement solutions over traditional tracking methods.
In-Depth Regional Review
Asia-Pacific remains a hyper-competitive powerhouse driven by mobile-first gaming habits in Southeast Asia and East Asia, utilizing advanced supply-side and demand-side platforms. Meanwhile, Western markets focus heavily on retention optimization and identity resolution solutions to counter rising user acquisition costs on iOS and Android storefronts.
Strategic Positioning of Leading Companies
Industry leaders leverage distinct competitive moats: Google and Meta Platforms dominate social and mobile advertising platforms, while ironSource (via Unity) and AppLovin integrate game engines with robust mediation and cross-promotion networks. Attribution specialists like AppsFlyer and Adjust provide essential measurement solutions required by top-tier publishers.
Porter's Five Forces Analysis
Bargaining power of buyers is moderate to high, as large game publishers demand custom attribution terms from AdTech vendors. Threat of substitutes remains low given the technical complexity of programmatic advertising platforms, while competitive rivalry is intense among scaled players like Moloco, Digital Turbine, and Mintegral.
SWOT Analysis of User Acquisition For Games Market
Key strengths include advanced machine learning algorithms and robust SDK integrations. Weaknesses involve high dependency on walled-garden app store policies. Opportunities lie in expanding console and PC user acquisition automation, while severe threats stem from evolving global data privacy regulations and identifier deprecation.
Value Chain Analysis and Industry Structure
The value chain flows from raw data generation and software development kits (SDKs) through data management and attribution solutions, culminating in ad placement across supply-side platforms. Specialized agencies and consulting services bridge the gap between technical infrastructure and game publishers seeking optimized return on ad spend.
Investment Insights and Strategic Recommendations
High-potential investment areas include privacy-safe measurement solutions, AI-driven creative optimization tools, and cross-platform attribution platforms. Our analysis advises investors to target B2B software providers offering deterministic identity resolution and automated engagement tracking to capture outsized value as the market reaches 36.33 Billion by 2033.
Conclusion and Key Industry Takeaways
The User Acquisition For Games Market industry trends point toward an essential pivot toward automation, privacy compliance, and multi-channel diversification. With a projected CAGR of 14.10% through 2033, stakeholders must prioritize robust data analytics and strategic platform partnerships to thrive in a privacy-first gaming economy.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level executives at top gaming studios and AdTech firms, secondary trade registry data, and macroeconomic indicators. This multi-layered approach ensures precise financial modeling supporting our 14.43 Billion market size figure for 2026.
Scope of the Report and Coverage Parameters
This report covers global deployment of user acquisition tools, services, and platforms across mobile, PC, and console game types from 2027 to 2033. Limitations exclude unregulated underground grey-market ad networks and focus strictly on verified enterprise-grade monetization, retention, and campaign management solutions.
Recent Developments in the AdTech and Gaming Ecosystem
Recent strategic moves highlight aggressive M&A activity and product launches, with companies like Liftoff, InMobi, and Singular rolling out advanced SKAN 4.0 measurement solutions. Partnerships between major social media platforms and game distribution networks continue to reshape how programmatic advertising platforms handle audience segmentation and fraud prevention.